The Biggest Lie in Chiropractic Practice Sales
Cash at Close Is the New 8x Multiple
Chiropractors fucking love multiples.
“Practices are selling for 6x.”
“I heard somebody got 8x.”
“This group is paying 10x.”
“My buddy’s practice got valued at $7 million.”
Cool.
How much money actually hit his checking account?
Because those are two completely different conversations.
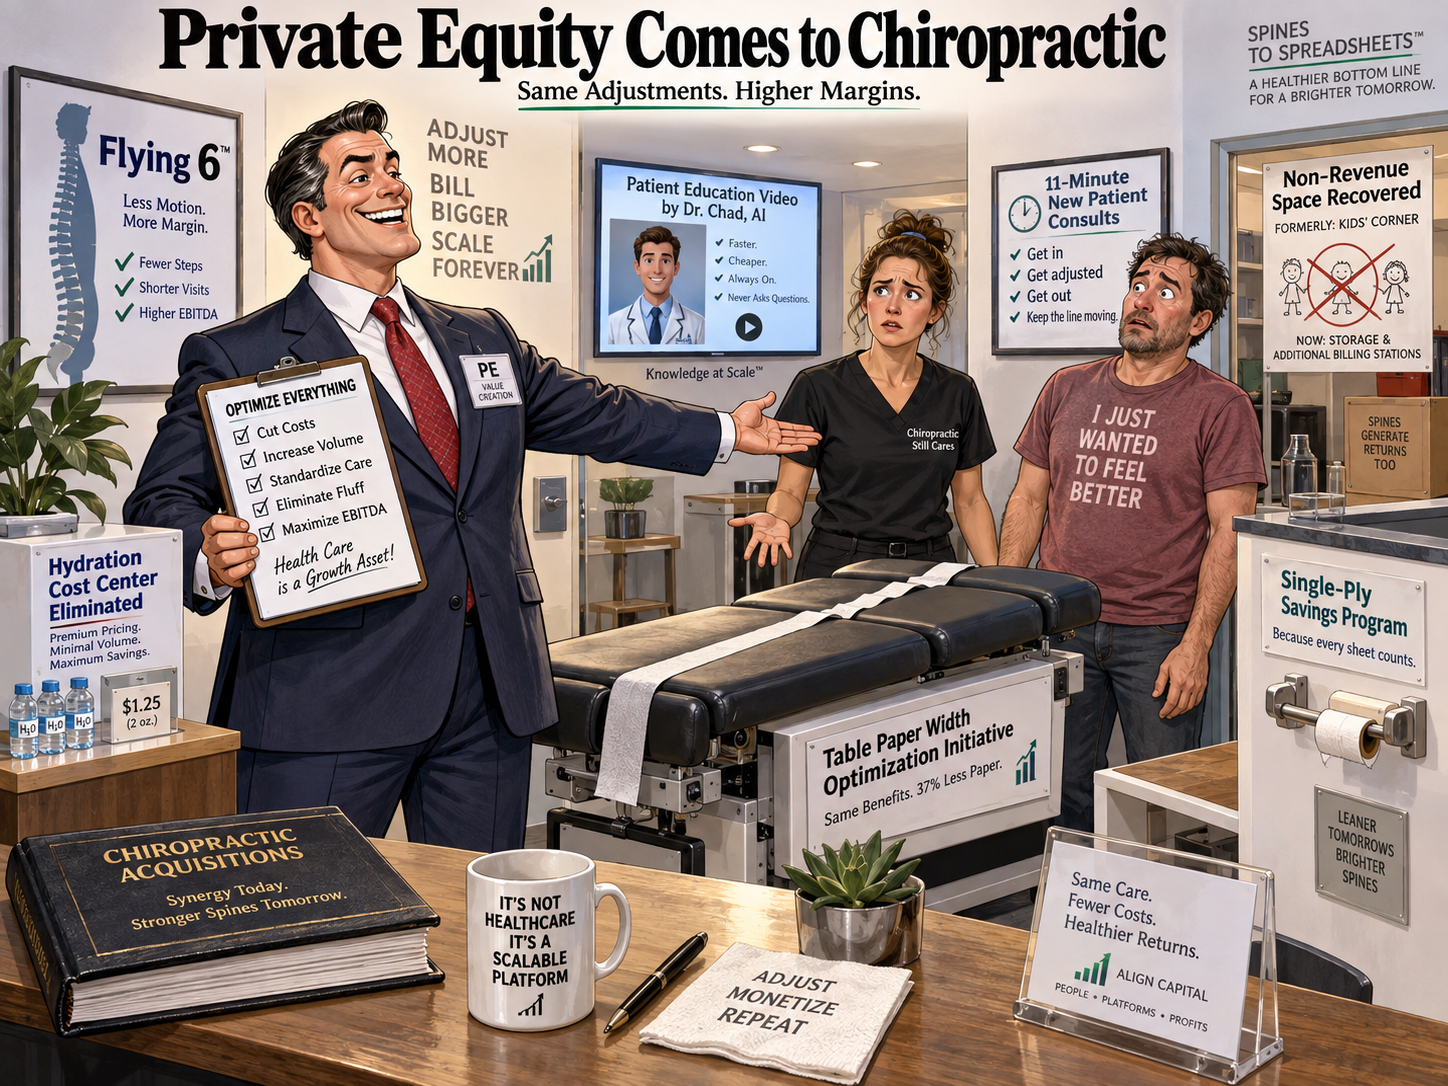
And I think chiropractic is going to have to learn the difference very quickly as more institutional money, consolidators, MSOs, strategic buyers and private equity-backed groups start sniffing around the profession.
We’ve become obsessed with the headline multiple.
But the headline multiple may be one of the least interesting numbers in the entire deal.
I Heard Something Recently That Changed How I Think About This
I was listening to a conversation between private equity investors discussing what has happened to their own industry as the easy-money era ended.
For years, money was cheap.
Interest rates were low.
Valuations expanded.
Buyers could pay aggressive prices and reasonably expect somebody else to pay an even more aggressive price later.
Then the environment changed.
And suddenly investors who had mentally penciled in a 3.5x return had a decision to make:
Take 2.5x today?
Or keep holding the asset hoping the old market eventually returns?
One of the investors basically said:
Take the fucking money.
Not because 2.5x was the dream.
Because 2.5x realized may be better than 3.5x imagined.
The conversation gets into how holding longer can actually deteriorate returns and how some investors remain anchored to exit multiples from a different economic environment.
And then came the line that I think translates beautifully to chiropractic:
“DPI is the new IRR.”
Private equity nerd language.
But here's what it means.
IRR can involve assumptions.
Valuations can involve assumptions.
Marks can involve assumptions.
Projected exits definitely involve assumptions.
DPI asks a much simpler question:
How much actual money did you get back?
As they put it in the conversation:
Cash doesn't lie.
And chiropractic desperately needs its own version of that.
I think it's this:
Cash at Close Is the New 8x Multiple.
Because an 8x deal isn't necessarily an 8x deal.
The Multiple Is Marketing Until You Read the Deal
Imagine two chiropractors.
Both own practices producing $500,000 in adjusted EBITDA.
Doctor A
Gets offered 8x.
Sounds incredible.
$4 million valuation.
He tells everybody at the mastermind:
“I sold for eight times EBITDA.”
But then you open the paperwork.
$2 million cash at close.
$1 million rolled into equity in the new company.
$500,000 tied to an earnout.
$500,000 contingent upon certain performance targets.
Three-year employment agreement.
Compensation changes after closing.
Noncompete.
Restrictions on what he can do next.
Certain decisions aren't his anymore.
And the rollover equity?
Maybe it doubles.
Maybe it triples.
Maybe it becomes worth less.
Maybe another transaction happens.
Maybe it doesn't.
The headline was $4 million.
The guaranteed cash that actually changed his financial life on closing day was $2 million.
Now meet Doctor B.
Same $500,000 EBITDA.
She gets 5x.
$2.5 million.
Doesn't sound nearly as sexy.
Except:
$2.25 million is cash at closing.
$250,000 gets held back for ordinary deal mechanics.
No giant earnout.
No fantasy valuation attached to private stock she can't sell.
Cleaner transition.
Better post-sale compensation.
Fewer restrictions.
Much clearer exit.
So who actually got the better deal?
You can't answer that by saying:
8x versus 5x.
That's exactly the problem.
There Isn't One Number in a Practice Sale
There are probably seven.
1. Headline Purchase Price
This is the sexy number.
This is what everybody talks about.
It's what ends up in the Facebook post.
“Practice acquired for $6.8 million.”
Wonderful.
But that's the beginning of the analysis.
Not the end.
2. Cash at Close
This is the money you actually receive when the transaction closes.
This matters.
A lot.
Because there is a massive difference between:
“My practice was valued at $5 million.”
and
“$4.2 million landed in my account.”
Those sentences may sound similar.
They aren't.
3. Rollover Equity
The buyer may ask you to reinvest part of your proceeds into the new parent company.
And rollover equity can be fantastic.
Seriously.
If the platform grows and sells again at a higher valuation, the “second bite of the apple” can potentially be enormous.
But it's not cash.
It's an investment.
Treat it like one.
You are now betting on:
the buyer,
their leadership,
their capital structure,
their acquisition strategy,
their debt,
their future multiple,
their ability to integrate practices,
their ability to retain doctors,
and whatever the market looks like when they eventually try to sell.
That's not necessarily bad.
But don't call it cash.
4. Earnout
This is my favorite.
“You sold your practice for $4 million!”
Well…
$700,000 of that requires hitting goals over the next three years.
So did you sell it for $4 million?
Or did you sell it for $3.3 million with an opportunity to earn another $700,000?
Those aren't the same sentence.
And if part of your purchase price requires you to continue producing the results that create the purchase price…
I'd want to understand that pretty damn well.
5. Your Compensation Afterward
This gets ignored constantly.
You sell.
Great.
What are they paying you to continue working?
Because occasionally part of the economics gets shuffled around.
Maybe the purchase price looks phenomenal but your post-transaction compensation becomes less favorable.
Maybe your compensation is great.
Maybe it's terrible.
Maybe you're required to hit production numbers.
Maybe your schedule changes.
Maybe you lose benefits you previously ran through the business.
Maybe you're required to remain for three or five years.
You can't analyze a sale without analyzing what happens to your income after the sale.
6. Restrictions
What are you giving up?
Can you practice nearby?
Can you start another healthcare business?
Can you market to your existing community?
Can you invest in another clinic?
What happens if you hate working for the new ownership six months later?
What happens if they fire you?
What happens if you quit?
What happens to your rollover equity?
What happens to your earnout?
Sometimes the most expensive thing in a deal isn't something the buyer takes from your purchase price.
It's something they take from your future optionality.
7. Actual Realized Wealth
And this is the number I'd eventually care most about.
Five years after closing:
What did the transaction actually produce for you?
Cash at close.
Plus eventual earnout received.
Plus rollover proceeds actually realized.
Plus compensation.
Minus taxes.
Minus deal expenses.
Minus whatever financial value was attached to commitments and restrictions you accepted.
That's the chiropractic version of DPI.
Not:
“What multiple did somebody say your practice was worth?”
But:
What did you actually get?
Chiropractors Are Going to Get Anchored to the Wrong Era
Here's another part of the PE conversation I think matters.
Some investors are still holding assets based on what those assets used to be worth.
They remember the old market.
They remember the old multiples.
They remember cheap debt.
They remember buyers tripping over each other.
And psychologically, they don't want to accept less.
So instead they wait.
And wait.
And wait.
Because selling for less than the number once written on a spreadsheet feels like losing.
Private equity investors in the podcast discuss exactly this phenomenon: people holding assets hoping previous multiples return, even though the exit environment has fundamentally changed.
Chiropractors will do the exact same thing.
Especially once stories start circulating.
“Joe got 8x.”
“Sarah got 9x.”
“That group was paying 10x two years ago.”
Great.
Joe's deal isn't your deal.
Sarah's practice isn't your practice.
And the market that existed when they sold may no longer be your market.
A buyer doesn't owe you yesterday's multiple.
The market doesn't care what your friend received.
And the number somebody once floated over dinner isn't an asset on your balance sheet.
Sometimes the smartest decision may be taking an excellent deal today rather than spending another five years trying to recreate a transaction that existed in a different market.
And sometimes the smartest decision is absolutely to hold.
That's the point.
The decision should be based on the complete economics—not ego around a multiple.
There's Another Chiropractic Problem: EBITDA Itself Can Be Bullshit
Before arguing about whether you're getting 5x, 6x or 8x EBITDA…
Let's figure out whether your EBITDA is fucking real.
Chiropractic practices are notorious for owner weirdness.
Personal vehicles.
Family members on payroll.
Travel.
Random expenses.
Owner compensation above or below market.
Rent paid to another entity you own.
Equipment leases.
Personal expenses flowing through the business.
Doctor production that disappears if you retire.
Marketing performed personally by the founder.
Relationships that exist solely because you've lived in the community for 25 years.
So the buyer isn't necessarily multiplying the number you think they're multiplying.
They're going to normalize it.
Then they're going to ask an even scarier question:
How much of this EBITDA survives without you?
Because $600,000 of EBITDA produced by a practice that runs without its owner is a very different asset than $600,000 of EBITDA where Dr. Rockstar personally generates 70% of collections.
Same EBITDA.
Different business.
And therefore potentially a very different valuation.
Your Practice Isn't Worth What You Built.
It's Worth What Transfers.
This may be the entire article right here.
Chiropractors often think buyers are purchasing the past.
Twenty-five years in practice.
40,000 patients seen.
Beautiful office.
Great reputation.
Awesome equipment.
Community involvement.
But the buyer is really purchasing the future cash flows produced by what survives the transition.
So I'd start thinking about valuation through one question:
What transfers?
Does your team transfer?
Do your patients transfer?
Do referrals transfer?
Does your reputation transfer?
Do your Google rankings transfer?
Do your marketing systems transfer?
Does your conversion process transfer?
Do your outcomes transfer?
Does your associate doctor production transfer?
Does the culture transfer?
Does your EBITDA transfer?
Does your growth rate transfer?
Or does half of it walk out the door when your name disappears from the schedule?
This is why making yourself unnecessary isn't just a lifestyle goal.
It's a valuation strategy.
The Highest Multiple Might Not Make You the Richest
This is the behavioral trap I think chiropractic is walking toward.
We're going to turn acquisitions into another dick-measuring contest.
“My buddy got 6x.”
“I got 7.5x.”
“Well I know somebody who got 9.”
Who gives a shit?
Show me the waterfall.
Show me the cash.
Show me the contingencies.
Show me the debt.
Show me what happens if the next transaction never occurs.
Show me what you're required to do afterward.
Show me the employment agreement.
Show me the earnout requirements.
Show me what happens if EBITDA drops.
Show me what happens to your rollover if you're terminated.
Show me the noncompete.
Show me the tax structure.
Then let's compare deals.
Because:
8x with half of it trapped behind assumptions may be worse than 5x with certainty.
And 5x cash today isn't automatically better than 8x with excellent rollover equity either.
That's not the argument.
The argument is:
Stop comparing deals using one fucking number.
Start Asking Better Questions
When somebody tells you they sold their practice for 8x, don't immediately ask:
“Who was the buyer?”
Ask:
How much was cash at close?
How much rollover?
At what valuation?
What class of equity?
What happens to that equity if you're terminated?
How much was earnout?
What controls whether you receive it?
How long are you required to stay?
What's your compensation afterward?
Who controls staffing?
Who controls marketing?
Who controls pricing?
Who controls the clinical model?
What are your restrictive covenants?
What guarantees did you make?
What happens if collections decline?
What's the debt structure above you?
When does the buyer expect another liquidity event?
And perhaps most importantly:
What does your life look like afterward?
Because maximizing enterprise value and maximizing your life aren't necessarily the same objective.
Don't Optimize the Sale. Optimize What the Sale Does for You.
This is where the conversation becomes bigger than finance.
Maybe you're 48.
You love practicing.
You don't want to retire.
You want $3 million off the table, but you also want to keep working.
That's one transaction.
Maybe you're 62.
You're exhausted.
Your kids don't want the practice.
You want to be fucking done.
That's another transaction.
Maybe you're 40.
You think the buyer is building a monster company and you're willing to roll 40% because you want another bite.
Different transaction.
Maybe you don't need liquidity at all and your business is producing $1 million annually with very little involvement from you.
Why sell?
There isn't one right answer.
Which is precisely why obsessing over the multiple is stupid.
The buyer has objectives.
You should too.
Build a Practice Worth Buying Even If You Never Sell It
And here's the irony.
Almost everything that makes a practice more attractive to a sophisticated buyer also tends to make it a better business to own.
Reliable financial reporting.
Clean books.
Strong management.
Low founder dependence.
Documented systems.
Strong associate retention.
Diversified patient acquisition.
Consistent conversion.
Recurring referrals.
Good margins.
Strong outcomes.
Brand equity.
Technology.
Predictable growth.
A succession plan.
None of those things require private equity.
You don't have to sell your practice to benefit from building something somebody would want to buy.
In fact, that may be the ultimate freedom:
Build the practice like you're going to sell it.
Then become financially strong enough that you don't have to.
Cash Doesn't Lie
The private equity guys said something that chiropractic should probably steal.
Cash doesn't lie.
I love that.
Because we've got plenty of imaginary numbers in this profession.
Imaginary valuations.
Imaginary patient values.
Imaginary ROI.
Imaginary growth.
Imaginary company worth.
Eventually reality clears everything up.
A buyer wires the money.
Or they don't.
The earnout gets paid.
Or it doesn't.
The rollover equity becomes liquid.
Or it doesn't.
The practice keeps producing without you.
Or it doesn't.
So when this acquisition wave gets louder—and I think it will—don't become mesmerized by the biggest multiple somebody can put on a PowerPoint slide.
Ask a much simpler question:
What actually becomes mine?
Because your practice didn't sell for 8x just because somebody wrote 8x at the top of the LOI.
The number that matters is what survives the waterfall.
What survives the contingencies.
What survives the transition.
What survives taxes.
And ultimately…
what ends up in your pocket.
That's why I think chiropractic needs a new bragging right.
Not:
“I got 8x.”
But:
“Here's what I actually realized.”
Because in the next era of chiropractic practice sales: